Not supported · Entries · 2026-10-11
Where the harmonic backtest sits against random buying and SPY
What this means
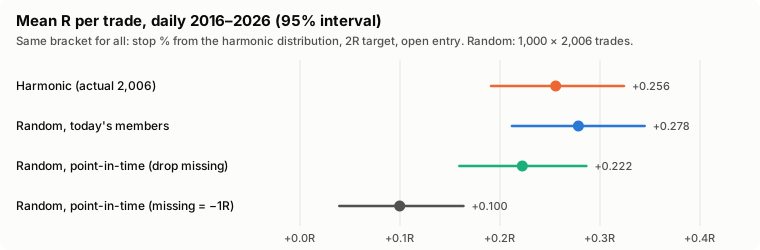
The backtest's headline gain over SPY is leverage plus a survivor universe, not the pattern. Per trade it matches random buying of the same names. Taken while the stock was a member, it earns +0.196R, below point-in-time random (+0.222R). At ~1× exposure it gives a SPY-like return with shallower drawdowns. That is weak at best and indistinguishable from luck against same-universe randoms. Trust SPY over the backtest.
Explanation checked against the data.
- Hypothesis
- The harmonic daily system's outperformance over SPY is not explained by survivorship and leverage alone.
- Method
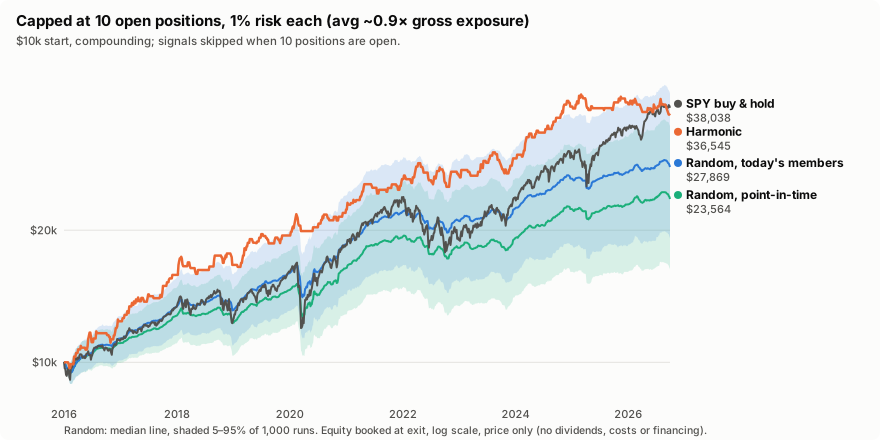
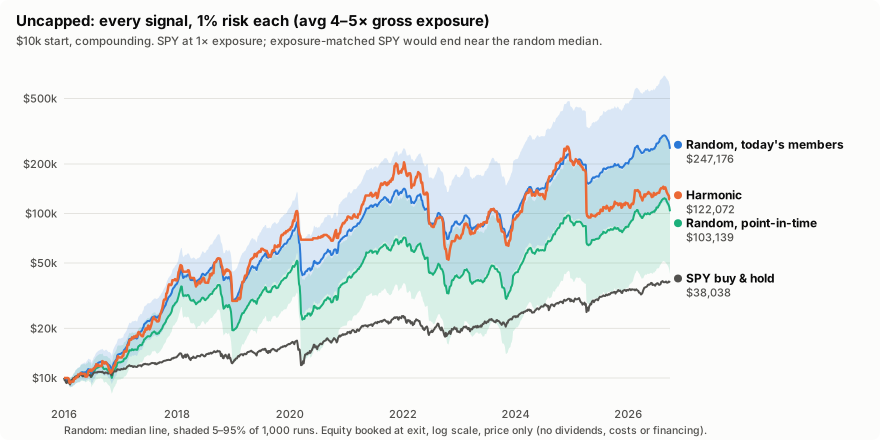
- The 2,006 actual harmonic daily trades run through the same account as 1,000 random systems on today's members and on the point-in-time index. Uncapped, and capped at 10 (harmonic: 1,000 orderings of same-day signals). Pre-registered decomposition: harmonic lead over exposure-matched SPY = pattern (harmonic − random today's) + survivorship (today's − PIT) + residual.
- Result
- Mean R: harmonic +0.256 (CI +0.19 to +0.32), random today's +0.278 (diff −0.02, CI −0.09 to +0.05). Uncapped: harmonic 26.2% CAGR at 4.1× vs exposure-matched SPY 35.4%; 10th percentile of today's random; MTM Sharpe 0.72 vs SPY 0.79. Capped: 12.8% (orderings 10.7–14.8%) vs SPY 13.2% / exposure-matched 12.9%; MTM MaxDD −16% vs −34%, MTM Sharpe 0.96. That is the 87th/90th percentile of today's random, not significant. Decomposition, CAGR pp, uncapped / capped: lead −9.2 / −0.1; pattern −8.6 / +2.8; survivorship +10.5 / +1.7. Trades on stocks already in the index at entry: +0.196R; not yet in the index: +0.611R (pit_check).
- How much to trust it
- Medium: Large random reference, exact trade reproduction. The capped result depends on which ~400 signals fit; one bull decade; no costs.
- Did it change the live rule?
- no live change; harmonics stay frozen for the forward test (review ~2027-04)
- Notes
- spy/RESULTS.md; the prereg rule says survivorship explains it uncapped and per trade, and not capped (pattern +2.8pp > survivorship +1.7pp, but n.s.).
Scripts and data for this study will be linked here when the research code is published on GitHub.
Education and research only. Not financial advice. Backtests use today's index members (survivorship bias).